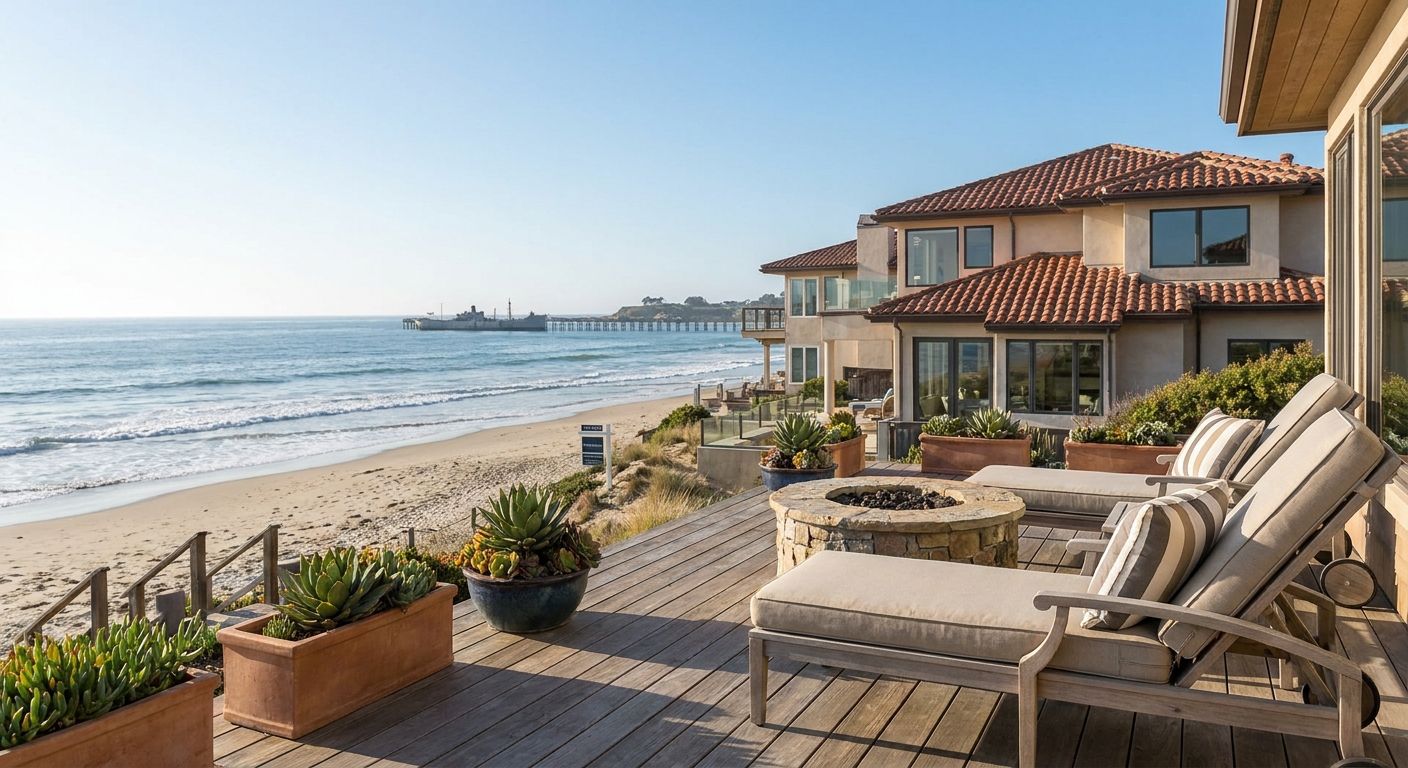
Rio del Mar sits on the Santa Cruz County coastline south of the city, and buying a beach home there means dealing with flood zones, coastal permits, and insurance rules that inland Santa Cruz shoppers never touch. This guide walks through the exact steps for closing on a beach property in Rio del Mar in 2026.
- Rio del Mar beach homes require flood insurance review before an offer goes in — skipping this step kills deals in escrow.
- Santa Cruz homes for sale on beach lots often fall under California Coastal Commission jurisdiction for remodels — check before you buy to renovate.
- Walter Stauss recommends geotechnical and septic inspections on Cliff Drive and Beach Drive properties specifically, given bluff exposure.
- Pre-approval plus a signed insurance quote should happen before touring homes in 2026's tight beach inventory.
Why this matters
A beach home in Rio del Mar isn't priced or insured like a standard Santa Cruz County listing. Lenders want proof of flood coverage before they'll fund a loan on anything near the Rio Del Mar State Beach flood zone, and some insurers won't write a policy at all without a recent geotechnical report.
Skip these checks and you'll find out about them mid-escrow, when you have far less leverage to renegotiate or walk. Buyers who plan for coastal-specific paperwork close faster and with fewer surprises at the closing table.
What you'll need
- A pre-approval letter that accounts for flood insurance and earthquake coverage in your monthly budget
- A California-licensed agent who has closed coastal transactions — Walter Stauss works Santa Cruz, Monterey, and Santa Clara Counties and can flag flood-zone and Coastal Commission issues before you write an offer
- A FEMA flood zone lookup for the specific parcel (not just the neighborhood)
- Contact for a geotechnical engineer familiar with bluff and slope conditions in Aptos and Rio del Mar
- A septic inspector, if the property isn't on public sewer
- Time: budget 30 to 45 days from accepted offer to close, longer if a coastal permit review gets triggered
The steps
1. Confirm your insurance numbers before you shop
Beach proximity in Rio del Mar puts many parcels in a FEMA-mapped flood zone, and lenders require flood insurance on any property in a designated Special Flood Hazard Area. Earthquake coverage through the California Earthquake Authority is a separate line item most inland Santa Cruz buyers skip entirely.
Get quotes for both before you start touring homes, not after you're under contract. Expected outcome: a real monthly housing number that includes insurance, not just principal and interest.
Common mistake: budgeting off a mortgage calculator alone and discovering the insurance premium during underwriting.
2. Map the micro-markets
Rio del Mar isn't one uniform market — Seascape sits above the bluff with HOA rules, while Beach Drive and Cliff Drive properties sit closer to sea level with different erosion exposure. Each pocket carries its own flood zone designation and permit history.
Walk the streets at different tide times if you can. Expected outcome: a shortlist narrowed to blocks, not just the neighborhood name.
Common mistake: treating all Rio del Mar listings as equivalent when elevation and setback from the bluff vary block to block.
3. Line up your inspection team early
Beach homes need inspectors that inland Santa Cruz purchases don't: a geotechnical engineer for bluff stability, a septic specialist if there's no sewer connection, and a general inspector who understands salt-air corrosion on roofing, siding, and mechanical systems.
Book these before you're in contract so you can move fast once an offer is accepted. Expected outcome: inspection contingencies you can actually complete inside a standard 17-day window.
Common mistake: waiting until after acceptance to find a geotech, then missing the contingency deadline.
4. Check Coastal Commission jurisdiction before you fall for the remodel potential
The California Coastal Act of 1976 gives the California Coastal Commission authority over development within the coastal zone, and much of Rio del Mar falls inside that boundary. Adding square footage, replacing a seawall, or even some fence and deck work can require a coastal development permit on top of the standard county permit.
Ask the listing agent for permit history on the parcel. Expected outcome: a clear picture of what you can and can't build before you write your offer, not after.
Common mistake: assuming a remodel is a simple county permit process because that's how it works two miles inland.
5. Write an offer with coastal-specific contingencies
A standard purchase contract works as a base, but beach-property offers in Santa Cruz County should include contingencies for the geotechnical report, septic certification (if applicable), and confirmation of insurability — not just financing and general inspection.
Have your agent build these in from the start rather than adding them after the seller has already accepted a cleaner-looking offer from another buyer. Expected outcome: contract terms that protect you if the flood zone or bluff report comes back unfavorable.
Common mistake: dropping contingencies to compete in a multiple-offer situation on a property you haven't fully vetted.
6. Move through escrow on a realistic timeline
Budget 30 to 45 days for a typical Santa Cruz County coastal escrow, longer if the insurer requests additional documentation on flood or wildfire risk. Mello-Roos special tax assessments, first established statewide under the Mello-Roos Community Facilities Act of 1982, apply to some newer developments in the area — confirm whether the parcel carries one before you close.
Expected outcome: funding and recording on schedule, with no last-minute insurance or disclosure surprises.
Common mistake: assuming escrow moves at the same pace as a standard inland transaction.
7. Close and set up coastal-specific maintenance
Once you own a beach home, salt air, wind-driven sand, and higher humidity accelerate wear on exterior paint, hardware, and HVAC units compared to inland Santa Cruz properties. Budget for more frequent exterior maintenance than you would elsewhere in the county.
Expected outcome: a maintenance plan that protects the investment rather than reacting to damage after the fact.
Common mistake: applying the same maintenance schedule you used on a prior inland home.
Get local guidance on Rio del Mar listings
Walter Stauss covers Santa Cruz, Monterey, and Santa Clara Counties.
Troubleshooting
- Insurer won't quote flood coverage. Get a current FEMA flood zone determination for the exact parcel — some properties sit just outside the mapped hazard zone even when neighbors don't.
- Geotech report flags bluff instability. Ask for a scope-and-cost estimate for stabilization work and renegotiate price or request seller credits before removing contingencies.
- Septic system fails inspection. Get a repair or replacement estimate in writing and factor it into your offer or request the seller handle it pre-close.
- Coastal Commission permit history is unclear. Request the parcel's permit file directly from the county planning department before you assume any remodel is straightforward.
- Multiple-offer situation on a beach listing. Keep insurance and geotech contingencies in place rather than dropping them; a clean offer that protects you beats a slightly higher one that doesn't.
- Mello-Roos or HOA fees show up late in disclosures. Request the preliminary title report and HOA documents (if applicable) at the start of escrow, not week three.
Tools and resources
- FEMA Flood Map Service Center for parcel-level flood zone lookups
- California Earthquake Authority for coverage quotes
- Santa Cruz County Planning Department for coastal permit history
- A geotechnical engineer with local bluff experience in Aptos and Rio del Mar
- Walter Stauss, Coldwell Banker Realty, for coastal-specific listing guidance across Santa Cruz, Monterey, and Santa Clara Counties
What to do next
Get a flood zone and insurance quote for any specific address you're considering before you tour it. A property that looks like the right santa cruz homes for sale on beach match can turn into a financing problem fast if the insurance numbers don't work — check that first, tour second.
FAQ
What is the best way to buy a beach home in Rio del Mar in 2026?
Confirm flood insurance and geotechnical conditions before you shop, then work with an agent who has closed coastal Santa Cruz transactions. Rio del Mar's flood zones and bluff exposure vary block to block, so parcel-level checks matter more than neighborhood reputation.
Is Rio del Mar better than other Santa Cruz beach neighborhoods?
Rio del Mar offers direct beach access and a mix of bluff-top and street-level lots, which suits buyers who want walkable sand without the density of downtown Santa Cruz. Seascape, just above it, adds HOA amenities but comes with its own fee structure.
How much does flood insurance cost on a Rio del Mar beach home?
Cost depends on the parcel's FEMA flood zone designation, elevation, and structure type, so get a quote for the specific address rather than estimating from a neighboring sale. Lenders require proof of coverage before funding on any property in a Special Flood Hazard Area.
Do I need a geotechnical inspection to buy a beach home in Santa Cruz County?
Yes, for properties near the bluff in Rio del Mar, Aptos, or similar coastal stretches. A geotechnical report identifies slope stability issues that a standard home inspection does not cover.
Does the California Coastal Commission affect remodeling a beach home?
Yes, properties within the coastal zone established by the California Coastal Act of 1976 may need a coastal development permit for additions, seawalls, or certain exterior work. Check the parcel's permit history before assuming a remodel is a standard county process.
How long does escrow take on a Santa Cruz beach property?
Plan for 30 to 45 days, longer if the insurer or lender requests additional flood or geotechnical documentation. Coastal transactions typically take longer than standard inland Santa Cruz County closings.
What is Mello-Roos and does it apply in Rio del Mar?
Mello-Roos is a special tax assessment authorized under the Mello-Roos Community Facilities Act of 1982, used to fund infrastructure in some California developments. Not every Rio del Mar parcel carries one, so confirm it in the preliminary title report before closing.
Who should I work with to buy santa cruz homes for sale on beach?
Work with an agent who has closed coastal transactions specifically, since flood zones, septic systems, and Coastal Commission rules differ from inland Santa Cruz deals. Walter Stauss, a Coldwell Banker Realty agent, covers Santa Cruz, Monterey, and Santa Clara Counties.
One last thing
The detail most buyers miss: a parcel's flood zone status can change between FEMA map updates, so a neighbor's older policy or premium tells you nothing about your specific address in 2026. Pull the current determination for the exact parcel before you get emotionally attached to the view.